
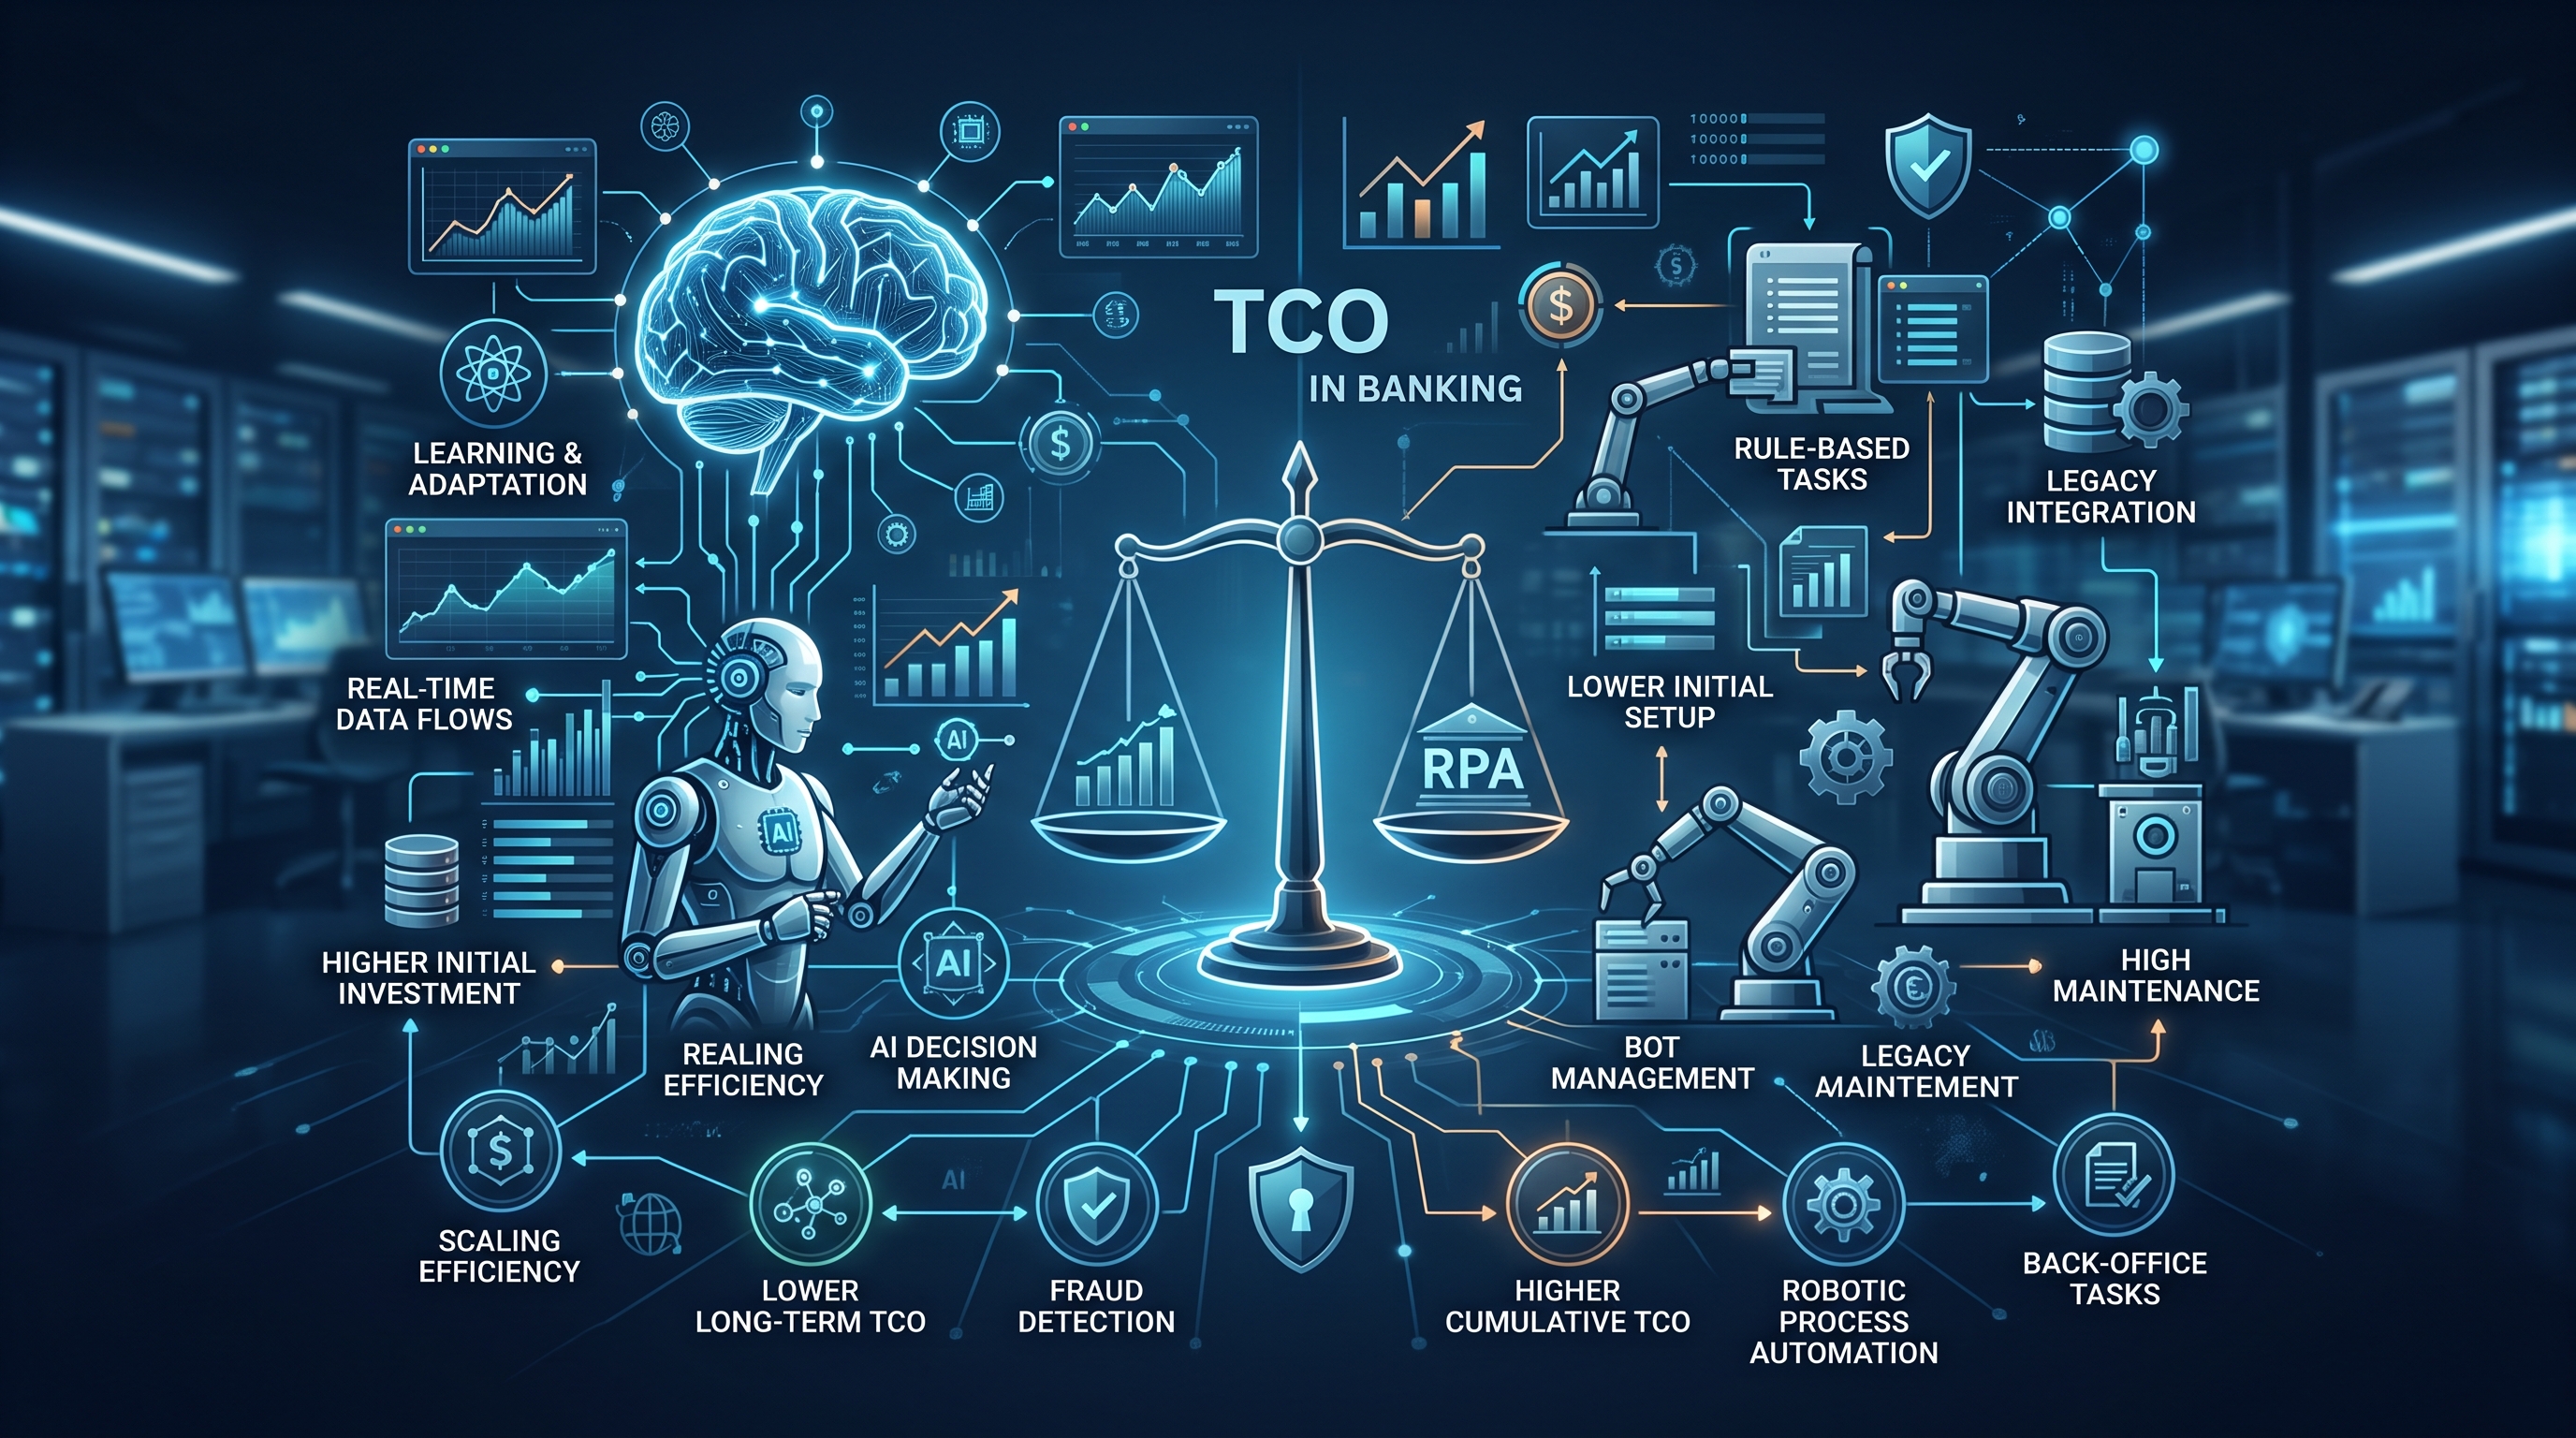
The Myth of Static Automation Costs
After two and a half decades in the trenches at institutions like JPMorgan Chase and Morgan Stanley, I have watched automation strategies cycle through hype. We moved from mainframe scripting to early RPA, and now we are racing toward agentic AI. The boardrooms are asking for the "total cost of ownership agentic ai vs rpa banking" comparison. They want to know if the heavy compute and governance overhead of large language models (LLMs) justifies the leap from rule-based bots.
The short answer is: it depends on your definition of "cost." If you only count license fees and server cycles, RPA often looks cheaper on paper. But if you count the engineering hours spent fixing broken selectors, the compliance risk of unverified outputs, and the opportunity cost of rigid workflows, the equation flips.
In my experience, RPA is a tool for stabilizing legacy processes. Agentic AI is a tool for redesigning them. You cannot compare their TCO without acknowledging that they solve fundamentally different classes of problems. RPA assumes the process is fixed. Agentic AI assumes the process is dynamic or requires judgment.
Deconstructing RPA Total Cost of Ownership
RPA vendors love to sell "zero-touch" automation. In reality, RPA is high-touch. The cost structure is heavily skewed toward maintenance. When a bank updates its core banking system’s user interface, hundreds of RPA bots break. This is not a bug; it is a feature of deterministic automation interacting with non-deterministic human interfaces.
The TCO for RPA includes:
- License Costs: Typically $1,500 to $2,500 per bot seat annually, plus developer licenses.
- Infrastructure: Dedicated worker nodes, often on-premise or in private cloud VPCs, requiring constant patching.
- Maintenance Labor: This is the silent killer. I have seen teams spend 60% of their time fixing broken scripts rather than building new value. A simple change in a dropdown menu can take hours to debug and redeploy.
- Error Handling: RPA bots fail hard. They do not recover gracefully. They email alerts, requiring human intervention to resolve edge cases.
The infrastructure is cheap, but the operational drag is immense. You are paying for stability in a changing world. If your banking processes are static and well-defined, RPA’s TCO remains low. But if your processes require interpretation, RPA becomes expensive because every exception requires a new rule.
The Hidden Costs of Agentic AI
Agentic AI is not just "smarter RPA." It is a probabilistic engine. The cost structure here is inverted. Upfront infrastructure and governance costs are high, but marginal maintenance costs can be lower if the system is designed correctly.
The primary cost drivers for Agentic AI include:
- Compute and Inference: Running LLMs, even distilled ones, consumes significant GPU/CPU resources. A single complex reasoning task can cost cents, which adds up across millions of transactions.
- Orchestration Overhead: You need a control plane to manage agent state, memory, and tool usage. This is where many banks fail. They build agents without a robust control plane, leading to unmanageable complexity.
- Governance and Audit: Every agent action must be logged, verifiable, and auditable. This requires a significant investment in observability and compliance frameworks, as detailed in our governance frameworks post.
- Training and Fine-tuning: While zero-shot prompting works for simple tasks, banking requires domain-specific accuracy. This demands fine-tuning or RAG (Retrieval-Augmented Generation) pipelines, which add engineering labor.
Unlike RPA, where a broken bot is a discrete failure, an AI agent might produce a subtle hallucination that passes initial checks but fails downstream. The cost of detection and correction is higher, but the cost of *prevention* through good architecture is lower than the perpetual fix-cycle of RPA.
Where the TCO Crosses Over
The crossover point is rarely about technology; it is about process volatility. In my analysis of enterprise implementations, I find that RPA remains cost-effective for processes with high volume and low variance. Think of standard KYC (Know Your Customer) checks where the inputs are structured and the rules are static. Here, RPA’s TCO is lower because the maintenance burden is minimal.
However, for processes involving unstructured data, multi-step reasoning, or frequent regulatory changes, Agentic AI wins on TCO. Consider loan underwriting. The rules change quarterly. RPA bots would require constant re-engineering. An agentic system can be prompted with new guidelines and adapt with minimal code changes.
The key metric here is "Mean Time to Adapt." For RPA, this is weeks. For Agentic AI, it can be days. Over a five-year horizon, the labor savings in development and maintenance for AI outweigh the compute costs, provided you manage the governance overhead effectively.
Implementation Risks and Mitigation
Bringing Agentic AI into a banking environment introduces risks that RPA does not. The most significant is the "black box" nature of model outputs. You cannot easily trace why an agent made a specific decision in a chain of thought. This is a compliance nightmare for regulators like the OCC or ECB.
To mitigate this, you must implement rigorous incident response protocols. We discuss this extensively in our incident response guide. You need a circuit breaker that can halt an agent chain if confidence scores drop below a threshold. This requires a mature SRE culture, which many traditional banking IT teams lack.
Furthermore, you must consider the "hallucination tax." If an agent makes a mistake, the cost is not just a failed transaction; it is regulatory fines and reputational damage. RPA errors are usually operational (failed transaction). AI errors are strategic (wrong decision). The TCO calculation must include a risk premium for these potential liabilities.
Frequently Asked Questions
Is Agentic AI more expensive than RPA in the first year?
Yes, typically. The initial setup for a secure, governed Agentic AI environment requires significant investment in control planes, security audits, and infrastructure. RPA can be deployed in weeks with lower upfront capital. However, RPA’s annual maintenance costs are higher, often eroding this initial advantage by year two or three.
Can we use RPA for unstructured data tasks?
Not effectively. RPA relies on deterministic selectors. If the input is an email, a PDF, or a scanned form, RPA cannot interpret the content. It can only extract text using OCR, but it cannot understand context. Agentic AI is required for tasks that require reading, summarizing, and reasoning about unstructured data.
How do we handle the compute costs of LLMs?
Use distilled models for routine tasks and reserve larger models for complex reasoning. Implement caching for repeated queries. Also, consider hybrid architectures where RPA handles the high-volume, low-complexity steps, and AI handles the exception handling and decision-making. This optimizes the total cost of ownership agentic ai vs rpa banking balance.
What is the biggest hidden cost in AI automation?
Governance. The cost of ensuring that every agent action is compliant, auditable, and secure is often underestimated. Banks must invest in robust logging, monitoring, and legal review processes. If you skip this, the cost of a single compliance breach will dwarf any savings from automation.